Counterfeit Check Scams: How to Protect Your Business
Counterfeit check scams: how overpayment scams reach businesses, why a deposited check can be fake after funds show as available, and what to do.
The short answer
A counterfeit check scam sends a business a fake check, often for more than it owes, and asks for money back. Banks must release deposited funds quickly under Regulation CC, but “available” does not mean the check is good. When the bank finds the fake, it can take the money back, and you may be left repaying it. Do not send money from a check until you have verified it with the issuing bank.
At a glance
- A fake check can look real even to bank staff. The FTC says it can take weeks for a bank to find it.
- Under Regulation CC a bank must release part of a deposit by the next business day, but it may hold a check it has reasonable cause to doubt (12 CFR 229.10, 229.13(e)).
- When a check is returned, the bank can charge the amount back to your account (UCC 4-214), and the FDIC says you will likely be held responsible for the money you sent.
- An overpayment with a request to refund the difference is the standard warning sign. The FTC calls it a fake check scam.
- Report to the FTC and to the FBI’s IC3. If the check came by mail, also report to the U.S. Postal Inspection Service.
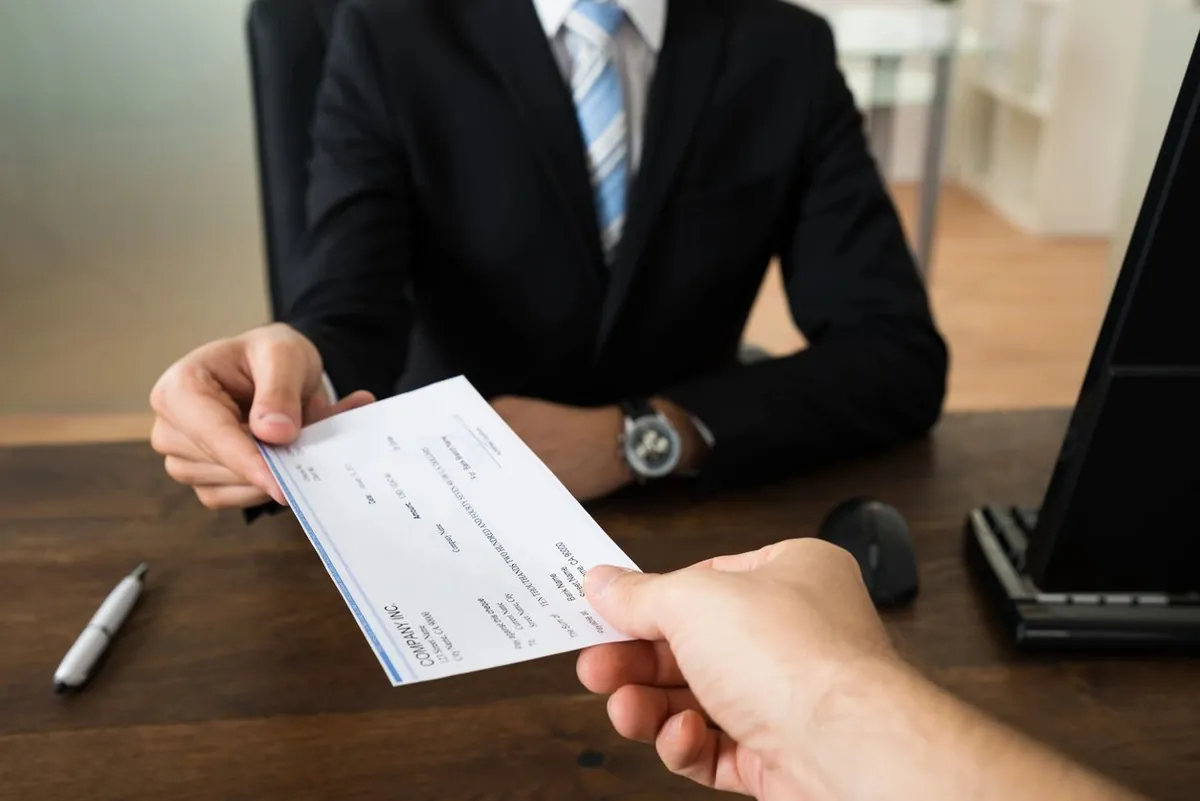
How the scam reaches a business
The FTC describes the small-business version: a customer pays by check, the check is for more than the price, and the customer asks you to send the difference back. The FTC says this is a fake check scam even when it looks like a normal refund request. The FTC and the FDIC list other cover stories too, such as overpayment on online sales or rentals, fake jobs, mystery shopping and prizes. In each case the sender asks you to send some of the money back or pass it to someone else.
The sequence is usually the same:
- A stranger or a new contact agrees to buy, hire or pay.
- A check arrives for more than the amount owed, with a reason: a mistake, a shipping fee or a third party who must be paid.
- The sender asks you to deposit it and send back the difference, or pay someone else, by wire, gift card or cryptocurrency, and to do it quickly.
- The bank makes the deposit available, so your balance looks good.
- Days or weeks later the check is returned as fake. The money you sent is gone, and the bank takes the deposit back.
Why “available” does not mean “good”
Regulation CC sets how fast a bank must release deposited funds. Cash and electronic payments must be available by the next business day. Cashier’s, certified and teller’s checks are also next-day when they are deposited into the payee’s own account, in person, and meet other conditions. For other checks, the first $275 of a day’s deposits is next-day (12 CFR 229.10).
Fast access to funds is not a decision that the check is valid. The FTC puts it this way: “Even if you see the funds in your account, that doesn’t mean it’s a good check.”
A bank may delay funds when it has reasonable cause to believe a check is uncollectible. That needs facts that would cause a well-grounded belief in the mind of a reasonable person, and the bank must give a written notice that states the reason (12 CFR 229.13(e) and (g)). Other holds apply to new accounts and large deposits. The current text sets the threshold at $6,725 (12 CFR 229.13(a) and (b)).
If the check is returned, the collecting bank can revoke the credit and charge the amount back to its customer’s account (UCC 4-214(a)). The FDIC warns that if a check is found to be counterfeit, “you will likely be held responsible for the funds that were provided to the scammer.”
Warning signs
- The check is for more than you are owed, and you are asked to return the difference.
- The payer is someone you do not know, or the check comes from a third party or an unrelated company.
- You are asked to send money by wire, gift card or cryptocurrency before the check is verified.
- The bank’s name is unfamiliar, or the postmark does not match the issuing bank’s city and state (FDIC).
- Security features such as watermarks or security threads look poorly made (FDIC).
- The sender will not meet or speak with you directly, or presses you to move money at once.
How to protect your business
- Do not rely on money from a check, or send money out because of it, unless you know and trust the payer.
- Do not accept a check for more than the price. Return it and ask for a correct payment instead of refunding the difference.
- Verify the check. Find the issuing bank’s phone number on its official website, not on the check, and ask the bank to confirm the check number, date and amount. The FDIC’s BankFind tool shows whether a bank is FDIC-insured.
- Ask your own bank for its funds-availability policy and for the notice it gives when it places a hold.
- For new customers, choose a payment method you can verify before you ship goods or start work. See Getting paid by U.S. buyers.
- Write a rule for staff who open mail or make deposits: no refund and no return of an overpayment until the issuing bank has verified the check.
If you already deposited the check or sent money
- Stop sending money. Do not answer further requests from the sender.
- Call your bank at once. Tell it which check you deposited, what you sent and how you sent it (wire, card or cryptocurrency), and ask what it can do.
- Keep everything: the check, the envelope with the postmark, e-mails, texts, invoices and payment receipts.
- Report the scam to the agencies below.
- Expect that the bank may charge the returned check back to your account. If the bank demands repayment, read your deposit agreement and talk to a lawyer about your options.
Where to report
- FTC: ReportFraud.ftc.gov.
- FBI Internet Crime Complaint Center (IC3): complaint.ic3.gov, the FBI’s intake for cyber-enabled fraud and scams.
- U.S. Postal Inspection Service, if the check came by mail.
- Your state attorney general or local consumer protection agency.
- The bank named on the check, and the website or service where you met the sender, so they can block the person (FDIC).
Who handles this
Nora Busra Turan
Partner · Attorney
Murat Erdoğan
Partner · Lawyer, Istanbul Bar (Turkey)


Counterfeit check scams: questions people ask
how long does it take for a fake check to bounce
A fake check can take days or weeks to bounce; the FTC says a bank may take weeks to find a counterfeit. Regulation CC makes a bank release part of a deposit by the next business day (12 CFR 229.10), but available funds do not mean a good check. Verify the check with the issuing bank.
do i owe the bank if a check i deposited was fake
Usually yes. A collecting bank can charge a returned item back to its customer under UCC 4-214, and the FDIC says you will likely be held responsible for money you sent to the scammer. Your deposit agreement and the facts matter. Merit Law LLP in Houston can review a large loss.
can a cashier's check be fake
Yes. The FDIC and the FTC warn that scammers send counterfeit cashier's checks that can look real even to bank staff. Verify any check with the bank named on it, using a phone number from the bank's official website. An attorney reviews the facts if money is lost.
customer overpaid by check and asked for a refund is it a scam
An overpayment with a request to send back the difference is the standard sign of a fake check scam, says the FTC. Do not refund by wire, gift card or cryptocurrency, or before your bank confirms the check is good. A genuine payer can send a corrected payment. An attorney reviews the facts.
where to report a counterfeit check scam
Report a counterfeit check scam to the FTC and to the FBI's Internet Crime Complaint Center (IC3). If the check came by mail, also report it to the U.S. Postal Inspection Service, and tell your bank at once. Reporting does not decide who bears the loss; that depends on your deposit agreement.
Sources and review date
Fees and rules reviewed 26 Oct 2026. Sources below.
- 12 CFR 229.10, Next-day availability (Cornell LII)
- 12 CFR 229.13, Exceptions (Cornell LII)
- FTC Consumer Alert, Fake check scams and your small business
- FTC, How to spot, avoid, and report fake check scams
- FDIC Consumer News, Beware of Fake Checks (August 2019, updated 2022)
- UCC 4-214, Right of charge-back or refund (uniform text, Cornell LII)
- FBI, Internet Crime Complaint Center (IC3)
What changed: moved from the firm’s earlier blog and rewritten for business owners, not law firms (the earlier post warned law firms about fake clients and trust accounts); added how Regulation CC availability and charge-back work, the FTC, FDIC and IC3 guidance and a response checklist; removed the Canadian insurer source; checked on 26 October 2026.
Holding a check you are unsure about?
Monday to Friday, 8:00 a.m. to 5:00 p.m., office local time. We reply in English, Turkish and Chinese.